Company Spotlight · Sponsored
HL Hunt's SellFi Adds Credit Bureau Reporting and Auto-Generated TILA Disclosures to Its Seller-Financing Pitch
Beyond the "be your own lender" framing covered when SellFi first appeared on this site, the platform's own product page details flat-fee tiered pricing, AI-generated legal contracts, and an optional handoff to HL Hunt's AI debt-collection product when buyers fall behind.
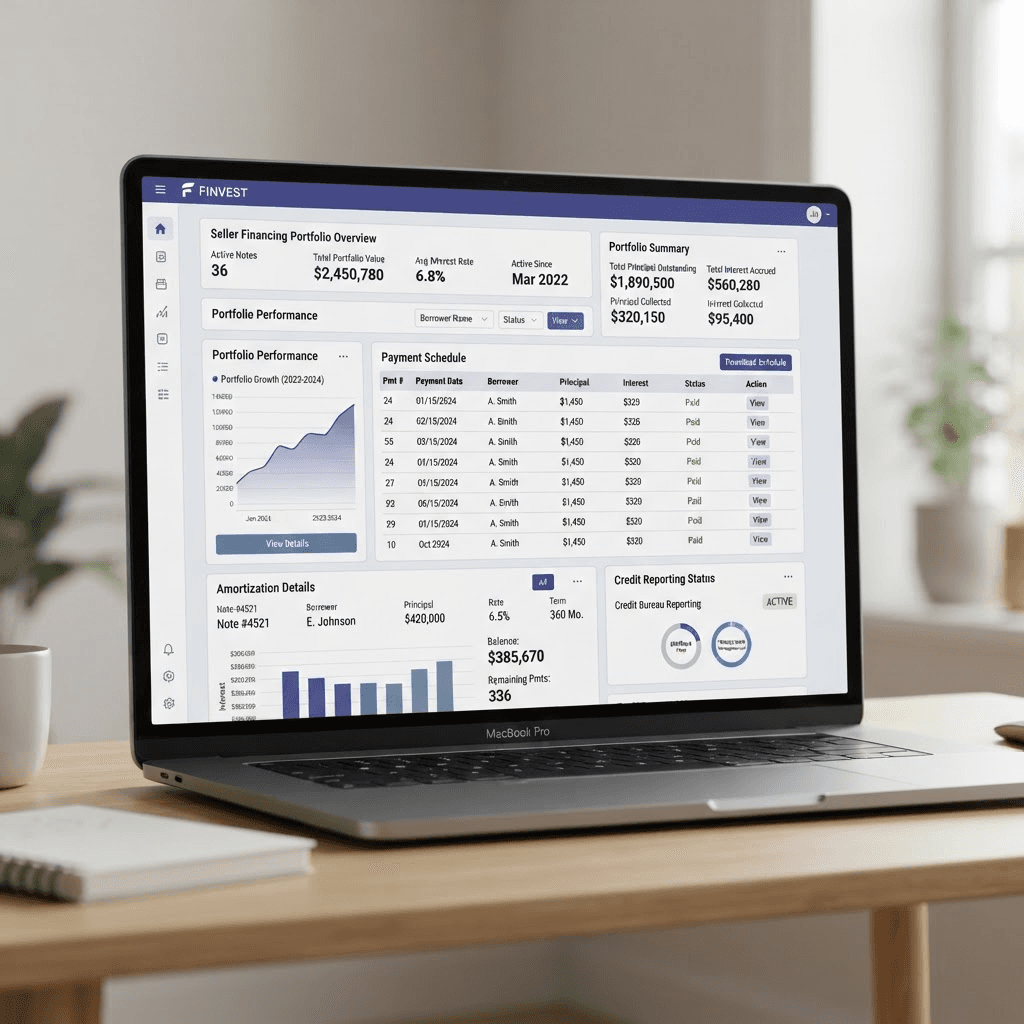
SPONSORED CONTENT — When SellFi first appeared on this site, the product was still pre-launch and the coverage focused on the "be your own lender" pitch and the credit-risk questions inherent in seller financing. HL Hunt's product page has since filled in more of the operational and pricing detail, and several pieces are worth noting on their own: the platform prices itself as a flat monthly subscription rather than a percentage of financed deals, at $29 a month for up to 10 active deals, $79 a month for up to 50, and a custom Enterprise tier for larger operations.
The platform says it auto-generates a state-compliant financing agreement, a promissory note, and a Truth in Lending Act (TILA) disclosure — covering APR, finance charge and total of payments — for every deal a seller creates, along with a built-in e-signature flow for the buyer. Whether an auto-generated contract actually satisfies state-specific seller-financing and lending disclosure requirements in every jurisdiction a seller might operate in is not something the product page substantiates beyond the marketing description; sellers extending credit are still personally responsible for legal compliance regardless of what a software vendor's template claims to cover.
On the Business and Enterprise tiers, SellFi offers optional reporting of payment activity to Equifax, Experian and TransUnion through HL Hunt's own Metro 2 reporting product — the same infrastructure HL Hunt sells as a standalone tool to lenders, covered separately on this site. For a seller-turned-lender, that reporting is pitched as an incentive tool to encourage on-time payments from buyers, though it also means the seller is taking on the administrative and compliance obligations of a data furnisher to the credit bureaus, not just a private creditor.
When buyers miss payments, SellFi says it automatically applies late fees under the contract's terms and escalates through a sequence of reminder notices, with an optional one-click handoff to HL Hunt's separate AI debt-collection engine if the seller wants to pursue recovery. HL Hunt's own site still labels the whole SellFi product "Coming Soon" and states explicitly that "all figures presented are forward-looking estimates" because the product "has not yet launched" — a caveat worth weighing against the polish of the dashboard mockups and deal-portfolio figures shown elsewhere on the same page.