Company Spotlight · Sponsored
HL Hunt Tells Business Credit Builder Members to Commit for a Full Year. Here's What It Says Happens If You Don't.
The company's own site frames early cancellation as a way to "erase the investment," walking through a month-by-month timeline that ties its highest advertised outcomes — a 90 to 100 Paydex score and access to prime lending — to members staying subscribed for the full twelve months.
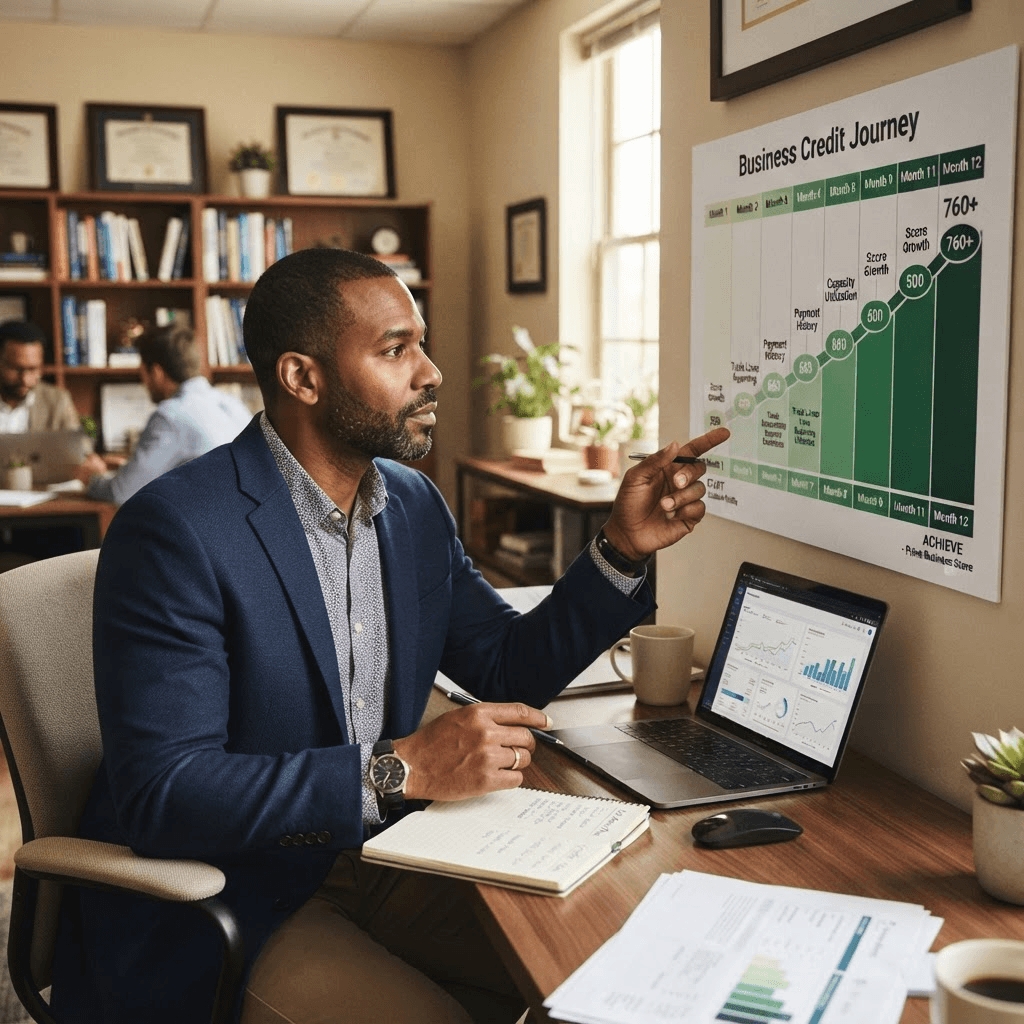
SPONSORED CONTENT — HL Hunt's Business Credit Builder page has been covered on this site before for its core mechanic: a revolving tradeline opened in the business's name, spending restricted to HL Hunt's own marketplace, and monthly payment history reported to bureaus in Metro 2 format. What that earlier piece didn't dwell on is a section of the same page devoted almost entirely to persuading members not to cancel — and the specific way HL Hunt frames that pitch is worth a closer look on its own.
The page includes a section titled "Why 12 Months Matters," complete with a "Risk Notice" stating that canceling early "can erase the investment." According to HL Hunt's own copy, quitting before the first year closes reduces available business credit and raises the utilization ratio, discards positive payment history before it fully weights a company's Paydex score, and permanently shortens business credit age — the site's wording is that this leaves a member with "investment wasted with minimal long-term score improvement to show."
The site backs this with a month-by-month timeline: months one and two are described as generating an initial Paydex score of roughly 0 to 80; months three through six unlock "starter" vendor accounts and revolving credit; months seven through nine open access to Tier 2 vendors and small bank loans; and months ten through twelve are where HL Hunt says members reach prime lending rates and a mature 90 to 100 Paydex score. A side-by-side comparison table on the page contrasts a "3-6 Months · Incomplete" tier against a "12+ Months · Mature" tier, with the latter marked with a star and the word "Recommended."
Membership pricing scales with the tradeline size a member wants reported: HL Hunt lists tiers starting at $9.99 a month for a $150 tradeline and running up to $199.99 a month for a $15,000 tradeline, with no setup or application fees and no stated penalty for canceling early beyond the credit-profile consequences described above. The company says the underlying tradeline carries a 0.00% APR and that it reports monthly, in Metro 2 format, to Dun & Bradstreet, Experian Business, Equifax Business and TransUnion.
HL Hunt's site also cites aggregate outcome figures for members: an average Paydex improvement of "+85 pts" in the first twelve months, an average of $250,000 in additional credit access gained, a 45-day average time to a first score increase, and a claimed 94% member satisfaction rate. None of these figures carry a stated methodology, sample size, or independent audit on the page, and MFN has not verified them.
The underlying claim — that longer, consistently-paid tradeline history produces better Paydex scores and more lending access than a short one — is consistent with how commercial credit scoring is generally understood to work, and is not unique to HL Hunt. What a prospective member can't verify from the marketing page alone is whether the specific score, dollar-access and timing figures HL Hunt attaches to its own product hold up as typical outcomes, or whether the framing of early cancellation as value destruction is doing more to describe a real credit-reporting mechanic than to discourage members from leaving a subscription before its annual value has fully materialized for HL Hunt.