Company Spotlight · Sponsored
HL Hunt's BaaS Product Lets Other Companies Offer Banking Without Becoming a Bank. Here's How It Works.
The banking-as-a-service offering routes checking and savings products through FDIC-insured partner banks, giving fintechs a white-label and API-level path into deposit accounts without holding a banking license themselves.
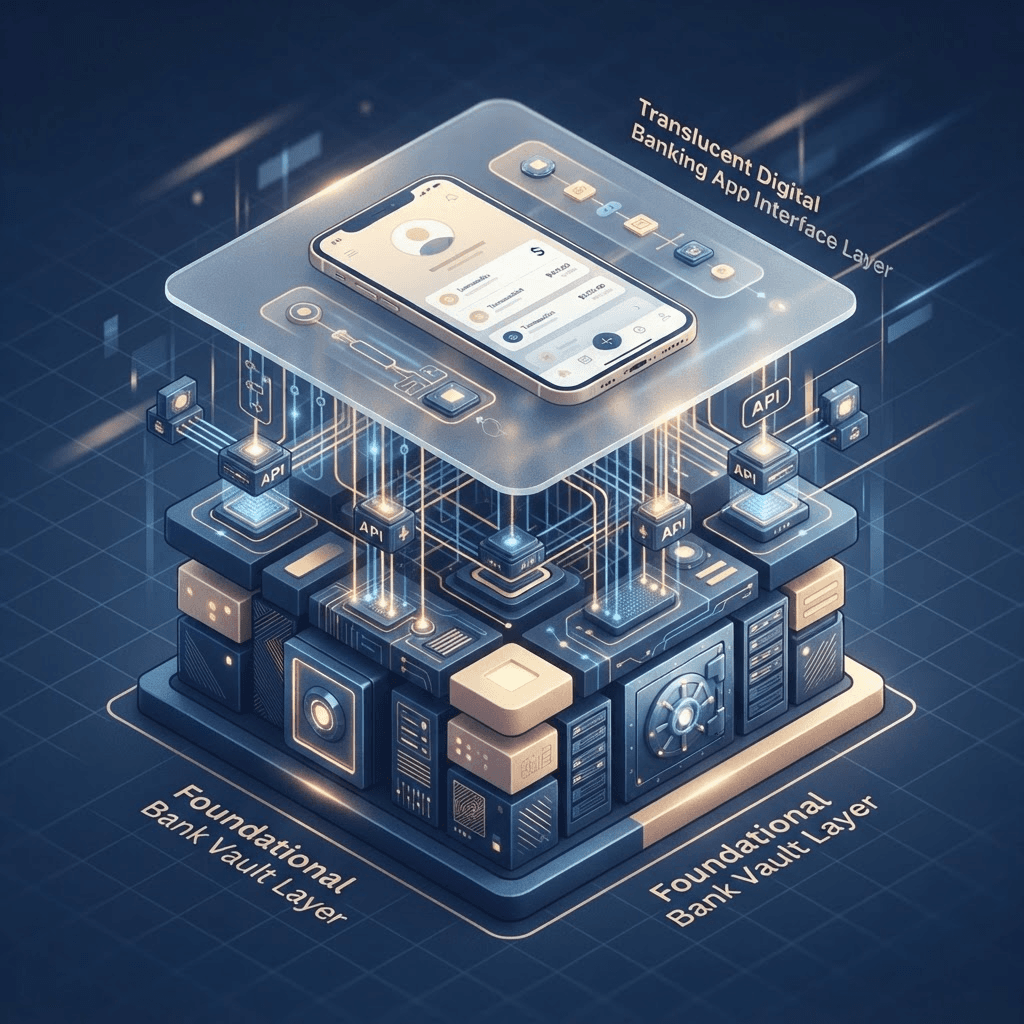
SPONSORED CONTENT — HL Hunt's Banking-as-a-Service product is pitched, per the company's own product page, as a way for other businesses to offer banking features — specifically checking and savings accounts — without going through the process of obtaining a banking license themselves. The structure is a common one in the BaaS category: HL Hunt sits between a client business and one or more FDIC-insured partner banks, with the partner banks actually holding customer deposits while HL Hunt handles the product, technology and compliance layer that sits on top.
The product page describes two levels of integration a client can choose: a white-label option, where a business can offer banking features under its own brand while HL Hunt and its partner banks handle the underlying infrastructure, and an API-level integration for companies that want to build more custom banking functionality directly into their own software rather than using a pre-built interface.
HL Hunt describes its compliance foundation as built on NMLS-registered lending entities, with what it calls documented end-to-end regulatory support — language aimed at businesses evaluating whether a BaaS partner can withstand regulatory scrutiny, an area of the industry that has drawn increased attention following a string of partner-bank failures and enforcement actions across the sector over the past several years. HL Hunt's public materials do not name its specific partner bank or banks, nor do they disclose deposit volumes, number of program clients, or the specific terms of its bank partnerships.
For a business evaluating any BaaS provider, the questions that matter most are usually the ones a marketing page cannot fully answer: which bank actually holds the deposits and what its regulatory standing is, how account funds are protected if the program or the partner bank relationship winds down, and what a client is contractually obligated to if the partnership changes. Those details are the province of due diligence and executed agreements rather than a product page, and HL Hunt's claims about its own compliance posture are its own representations, not independently verified by MFN.